Redundancy Advice

SECURE YOUR FINANCIAL FUTURE

REDUNDANCY & PENSION GUIDANCE IN IRELAND

Facing Redundancy? Make Informed Financial Decisions

If you’re facing redundancy, understanding your financial entitlements is crucial. Your redundancy package can significantly impact your pension and future financial security. Our expert advisors help you navigate your options to maximise tax-free benefits and secure your long-term financial well-being.

UNDERSTANDING YOUR REDUNDANCY ENTITLEMENTS

Your redundancy package typically includes:

Ex-Gratia Redundancy Payment

An additional, discretionary payment from your employer as a goodwill gesture.

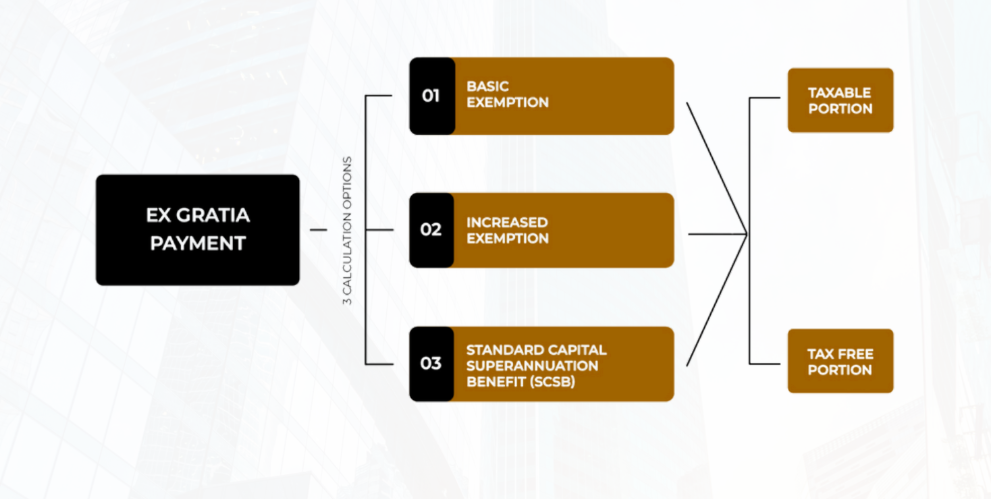
An additional, discretionary payment from your employer as agoodwill gesture. A portion is tax-free, but the remaining balance is subject to tax atyour marginal rate.

There are three methods to calculate the tax-free portion of your Ex-Gratia payment:Basic Exemption Tax-free amount: €10,160 + €765 for each completed year of service.

Redundancy Advice

Increased Exemption (if applicable)

Tax-free amount: €10,160 + €765 per completed year of service + €10,000. Available only if you have not received a payment above the basic exemption in the last 10 years. The extra €10,000 is reduced by any tax-free pension lump sum you have received or are entitled to receive.

Tax-free amount: (Average earnings over the last 36 months × years of service) ÷ 15, minus any tax-free pension lump sum you have received or are entitled to receive. This method can offer a higher tax-free sum, but you must decide whether to retain or waive your tax-free pension lump sum.

The SCSB calculation differs depending on whether you waive or retain your pension lump sum. If you retain it, the SCSB is reduced by the value of that lump sum. If you waive it, you get the full SCSB figure.

We will calculate each method for you and show which gives the highest tax-free amount, taking your pension into account.

How It Works

Your options when you leave employment

Step 1

PENSION TRANSFER OPTIONS AFTER REDUNDANCY

Upon leaving employment, you have several pension transfer options. Each choice impacts your tax benefits and accessibility to funds.

Step 2

Your Pension Transfer Choices

Leave it in your former employer’s scheme Transfer it to a new employer’s scheme (if available) Transfer it to a Personal Retirement Bond (PRB) Transfer it to a Personal Retirement Savings Account (PRSA) (for tax-free lump sum retention)

Step 3

Important Considerations

If you choose an increased tax-free redundancy payment by waiving your pension lump sum, you can only regain a tax-free lump sum if you transfer your pension into a PRSA. None of the other transfer options allow for a tax-free pension lump sum.
Immediate access to your tax-free lump sum

ARF

The remaining 75% can be transferred into an Approved Retirement Fund (ARF)

PRSA

Flexibility to leave funds in the PRSA if immediate access isn’t required

PRSA TRANSFER REQUIREMENTS: INDEPENDENT REPORT NEEDED

PRSA TRANSFERS: A TAX-EFFICIENT RETIREMENT STRATEGY

Transferring your pension into a PRSA ensures you retain your tax-free lump sum entitlement (25% of the transfer value). The first €200,000 (a lifetime limit across all your pensions) is tax-free, €200,001 to €500,000 is taxed at 20%, and anything above that is taxed at your marginal rate.

Standard retirement age: 60

Early access: From age 50, provided you are fully retired (i.e., no PAYE employment income).

Planning to return to work?

Retiring your PRSA before re-employment ensures: Immediate access to your tax-free lump sum

STEP-BY-STEP GUIDE: TRANSFERING FROM A PREVIOUS EMPLOYER INTO A PRSA

MAKE AN INFORMED DECISION WITH EXPERT GUIDANCE

Choosing the right redundancy and pension transfer option is essential to protect your financial future. Many redundancy package calculations overlook long-term pension implications, leading to costly mistakes. Our expert financial advisors provide personalised guidance to help you:

Get in touch with us

We’re here to help, reach out anytime for expert advice, personalised support, or answers to your financial questions.