How does the public sector pension work in Ireland? Public sector pensions in Ireland are defined benefit (DB) schemes, meaning your pension is based on your salary and years of service, not on an investment fund. If you joined the public service before 1 January 2013, you are likely on the old pre-existing scheme, which provides 1/80th of final salary per year of service plus a lump sum of 3/80ths of salary per year. If you joined from 1 January 2013, you are on the Single Public Service Pension Scheme (Single Scheme), which provides 1/60th of your career-average pensionable remuneration per year, with a full pension age of 66. Both schemes also allow Additional Voluntary Contributions (AVCs) to supplement the defined benefit with additional private savings.
Joe Coyle Financial Consultants, a CBI-regulated financial broker in Donegal and part of the Money Maximising Advisors group, provides specialist pensions advice Ireland for public servants across Ireland, including nurses, teachers, civil servants, local authority workers, Garda and HSE employees. Further guidance at Money Sense Financial Services.
The public sector pension is one of the most valuable financial assets a person in Ireland can have, but it is also one of the least understood by the people who hold it. Many public servants do not know which scheme they are on, how their pension is calculated, when they can retire, or how much their tax-free lump sum will be. This guide explains the two main schemes, the key differences, and the single most impactful thing many public servants can do to boost their retirement income: make Additional Voluntary Contributions (AVCs).
The Two Main Public Sector Pension Schemes in Ireland
The Old (Pre-2013) Public Sector Schemes
If you joined the public service before 1 January 2013, you are most likely on one of the pre-existing public sector pension schemes. Despite variation by sector (civil service, teachers, HSE, local authority, Garda, Defence Forces), most old schemes share common core features:
Pension accrual: 1/80th of pensionable pay for each year of service (sometimes 1/60th for certain grades or fast-accrual roles)
Lump sum: 3/80ths of pensionable pay for each year of service, this is taken tax-free at retirement
Full pension: Based on total service, 40 years of service produces a full pension of 40/80ths = 50% of final pensionable pay
Coordination: The pension is coordinated with the State Pension, meaning the defined benefit pension and the State Pension together provide the target income level
Retirement age: Varies by scheme, sector and joining date, many can retire from age 60, with some eligible from age 55
For example: a teacher with 35 years of service on a final salary of EUR 60,000 receives a pension of 35/80 x EUR 60,000 = EUR 26,250 per year, plus a lump sum of 3 x 35/80 x EUR 60,000 = EUR 78,750, all tax-free.
The Single Public Service Pension Scheme (Single Scheme)
The Single Scheme applies to all new public servants who joined from 1 January 2013. Its core features are different from the old scheme in several important ways:
Pension accrual: 1/60th of career-average pensionable remuneration for each year of service, the average is calculated across your entire career, not just your final salary
Lump sum: 3.75 times the annual pension accrued at retirement
Normal Retirement Age: Age 66, aligned with the State Pension age
Minimum Retirement Age: Age 55, but pension is reduced for early retirement before age 66
No coordination: The Single Scheme pension is not coordinated with the State Pension, you receive both independently
| Feature | Old Scheme | Single Scheme |
| Pension accrual | 1/80th of final salary/year | 1/60th of career avg./year |
| Lump sum | 3/80ths x salary x years | 3.75x annual pension accrued |
| Full pension age | 55 to 65 (varies) | Age 66 |
| State Pension | Coordinated (reduces DB pension) | Not coordinated (both paid in full) |
| AVC option | Yes, available | Yes, available |
► Get a Free Public Sector Pension Review, Book a Consultation
Can Public Servants Make Additional Voluntary Contributions (AVCs)?
Yes, and for many public servants, making AVCs is the single most impactful financial decision they can make in the years before retirement. AVCs allow you to supplement your defined benefit pension with a personal investment fund that you control, attracting full income tax relief at your marginal rate.
Why AVCs Are Particularly Valuable for Public Servants
Unused Revenue contribution room: Your defined benefit contributions count toward your Revenue age-related limit, but in many cases, the defined benefit alone does not fill the limit, leaving significant AVC headroom available
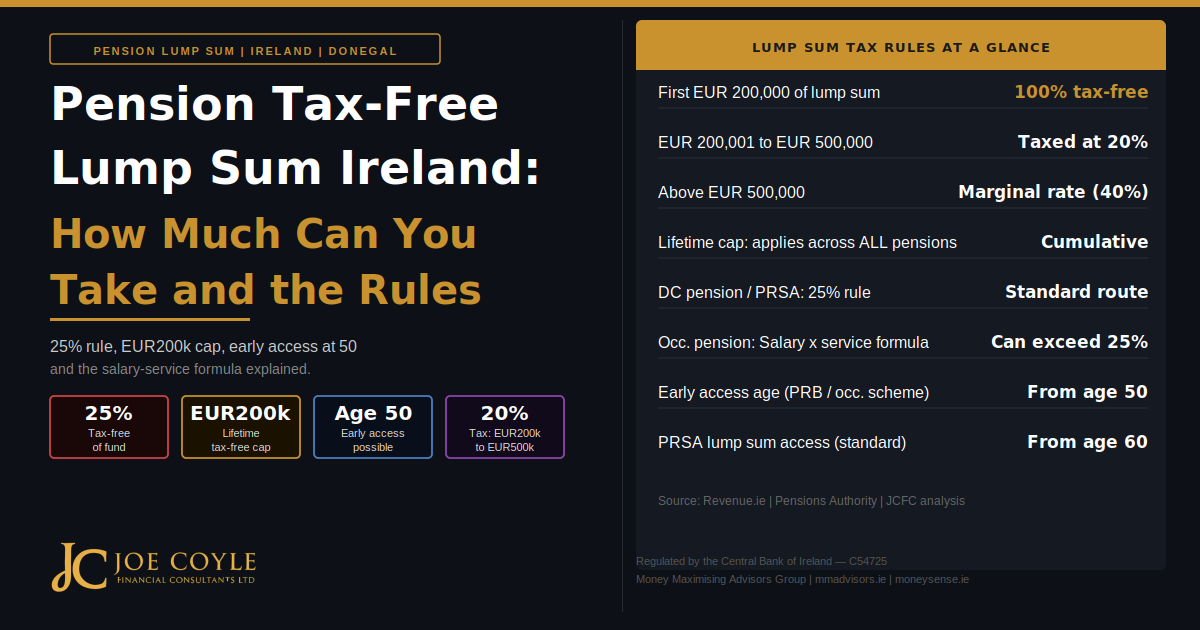
Tax-free lump sum maximisation: Revenue allows you to take a tax-free lump sum at retirement. The defined benefit lump sum alone may not reach the EUR 200,000 lifetime cap, AVCs can supplement this and be taken as an additional tax-free lump sum element
Flexible access: AVC funds can be taken at retirement as cash (tax-free up to the lump sum limit), invested in an ARF, or used to purchase an annuity, giving flexibility that the rigid DB pension structure does not
Catch-up contributions: Revenue’s age-related contribution limits rise with age, a 55-year-old can contribute 35% of earnings with full tax relief. Public servants in their 50s with unused headroom can make substantial catch-up AVCs
💡 A public sector nurse aged 50 on EUR 60,000 can contribute up to 30% of earnings (EUR 18,000 per year) to an AVC with full income tax relief. At the 40% tax rate, this costs EUR 10,800 net per year. Over 16 years to age 66 at 5% growth, this builds an AVC fund of approximately EUR 400,000, a substantial supplement to the DB pension.
At What Age Can a Public Servant Retire in Ireland?
The retirement age for public servants in Ireland depends on which scheme you are on and when you joined:
Old scheme (pre-2013), joined before 1995: Can retire without State Pension coordination at an earlier age, some can retire fully from age 55 or 60
Old scheme, joined between 1995 and 2004: Typically retire at 65, with coordination applying against the State Pension
Old scheme, joined between 2004 and 2012: Normal retirement age typically 65
Single Scheme (joined from 2013): Normal Retirement Age of 66. Minimum Retirement Age of 55, but pension is actuarially reduced for early retirement before 66
Cost-neutral early retirement: Many old scheme members can retire from age 55 on a cost-neutral basis, the pension is actuarially reduced to reflect the longer payment period, but no employer consent is required
How Is the Public Sector Pension Lump Sum Calculated?
The lump sum is one of the most valuable elements of the public sector pension package, and it is taken completely tax-free at retirement.
Old Scheme Lump Sum Formula
Lump Sum = (3/80) x Final Pensionable Pay x Years of Service
Example: 40 years of service on EUR 70,000 final salary: (3/80) x EUR 70,000 x 40 = EUR 105,000 tax-free lump sum.
Single Scheme Lump Sum
The Single Scheme lump sum is 3.75 times the annual pension accrued. For someone with 40 years of service on a career average of EUR 55,000: Annual pension = (1/60) x EUR 55,000 x 40 = EUR 36,667. Lump sum = 3.75 x EUR 36,667 = EUR 137,500 tax-free.
Frequently Asked Questions: Public Sector Pension Ireland
How does the public sector pension work in Ireland?
Public sector pensions are defined benefit (DB) schemes, your pension income is based on your salary and service, not on an investment fund. Old scheme members receive 1/80th of final salary per year of service. Single Scheme members receive 1/60th of career-average pay per year. Both schemes also allow AVCs for additional savings.
What is the Single Public Service Pension Scheme?
The Single Scheme applies to all new public servants from 1 January 2013. It provides 1/60th of career-average pensionable remuneration per year of service, with a normal retirement age of 66 and a minimum retirement age of 55 (with actuarial reduction). The lump sum is 3.75 times the annual pension accrued. Unlike the old scheme, it is not coordinated with the State Pension.
Can public servants make AVCs in Ireland?
Yes. AVCs allow public servants to supplement the defined benefit pension with a personal investment fund, attracting full income tax relief at their marginal rate. AVCs are particularly valuable for public servants with unused Revenue contribution room, those wishing to maximise the tax-free lump sum, and those making catch-up contributions in their 50s.
At what age can a public servant retire in Ireland?
It depends on the scheme and joining date. Old scheme members (pre-2004) may be eligible for cost-neutral early retirement from age 55. Single Scheme members have a Normal Retirement Age of 66 and Minimum Retirement Age of 55 (with actuarial reduction). Joe Coyle Financial Consultants advises on the optimal retirement timing for your specific scheme.
Is the public sector pension enough to retire on?
For many public servants, the DB pension plus State Pension provides a comfortable retirement income, particularly for those with full service under the old scheme. However, gaps arise for those with shorter service, those on the Single Scheme with a career average significantly below their final salary, or those who retire before the State Pension age. AVCs are the most effective way to address any gap.
► Get a Free Public Sector Pension Review, Joe Coyle Financial Consultants, Donegal
Important Information
This article is for general information only and does not constitute financial advice. Public sector pension scheme, AVC and retirement age information is correct at the date of publication. Joe Coyle Financial Consultants Ltd is regulated by the Central Bank of Ireland (C54725), part of Money Maximising Advisors (C154250). Always seek personalised advice from a Qualified Financial Advisor before making financial decisions.
Joe Coyle Financial Consultants Ltd | jcfc.ie | info@jcfc.ie | +353 091 342596
Part of Money Maximising Advisors Group | mmadvisors.ie | moneysense.ie